Real Estate IntelGet the free brief

Florida foreclosures and housing market

How foreclosure works in Florida, which counties lean to buyers or sellers, and how many homes are for sale right now.

How's the market in Florida?

A balanced market.

Listings spent about 79 days on the market, and 19% had a price cut in October 2026.

Market figures: Realtor.com® Economic Research, October 2026. Free weekly email. Unsubscribe anytime.

Distressed properties in Florida

Pre-foreclosures, auctions, bank-owned and HUD homes from county notices. Pick a status or tap a ZIP on the map. We show the street area, never the house number.

1property in FloridaUpdated Oct 3, 2026

© OpenFreeMap © OpenMapTiles © OpenStreetMap contributors · ZIP areas: US Census

Filter by ZIP

1 property match

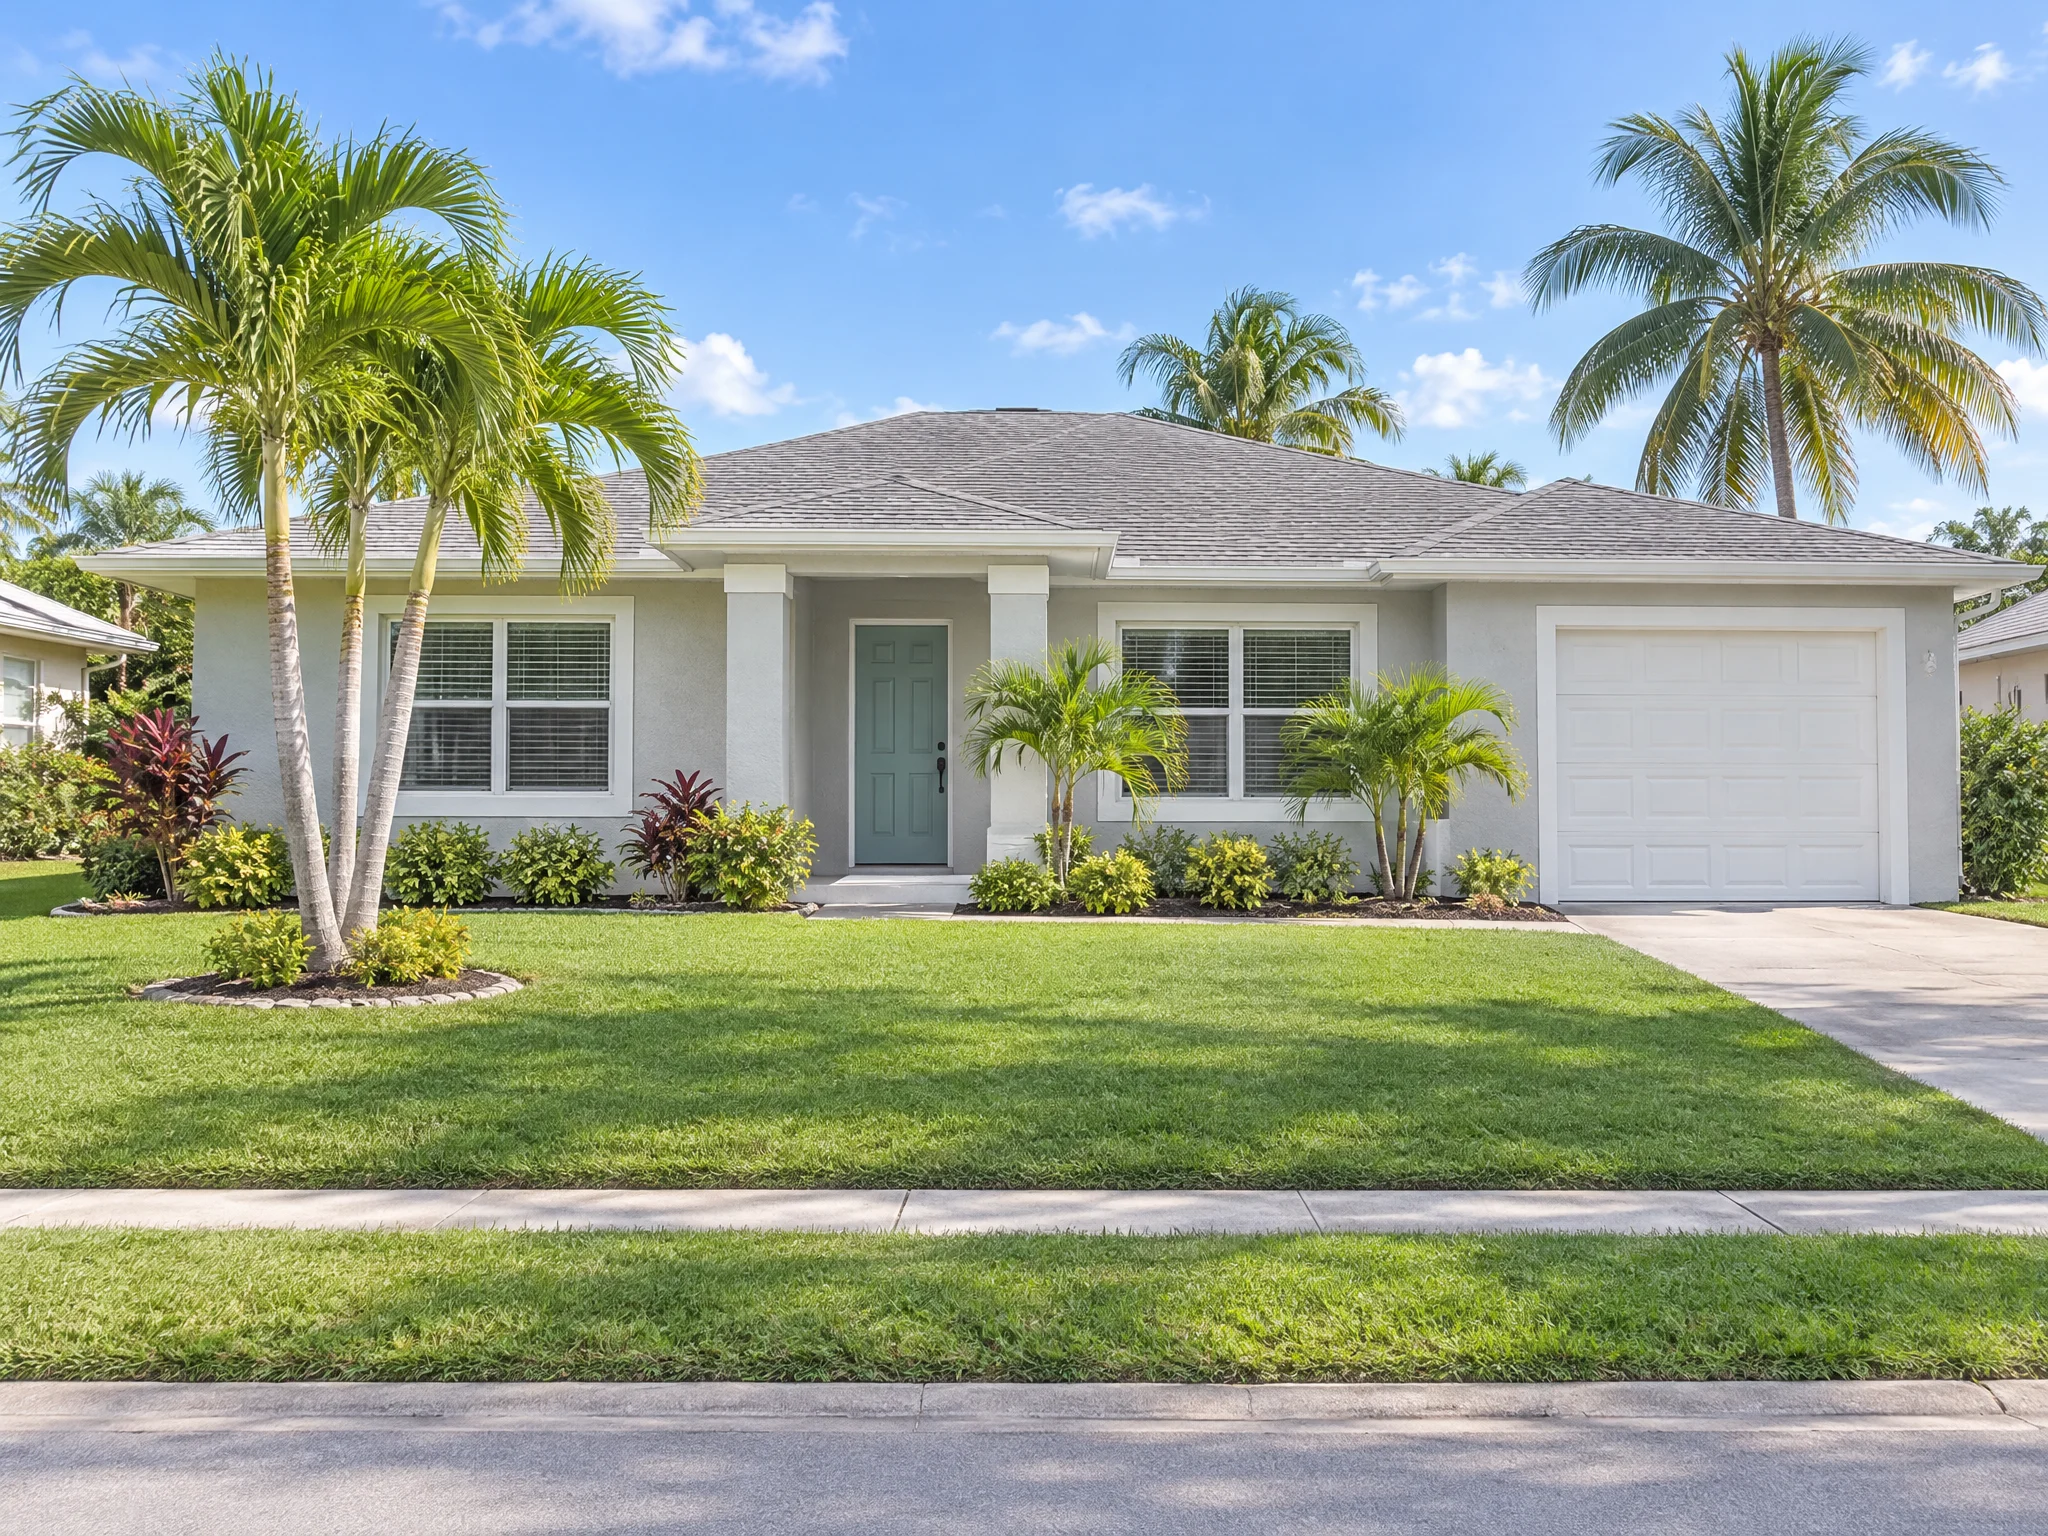
Block home with palms in FloridaHUD homeBids openRepresentative photo

S 37th Street area

Saint Petersburg, FL 33711 · Pinellas County

Single-family · $200K to $300K

HUD home: the FHA took this home back after a foreclosure and sells it through online bids.

Updated Oct 3, 2026
Source: county notices compiled by Real Estate Intel. Photos are representative, not the actual homes. Street areas only, never house numbers or owner names. Confirm every detail with the county before you act.

The Florida market in October 2026

Our score compares how many listings went under contract with how many were for sale, ranked against every US county. Low scores lean to buyers, high scores to sellers.

Florida market score

43Balanced market
Buyer's marketUS: 61Seller's market
Homes for sale
149,718
US: 1,179,101
Typical days on market
79
US: 66
Listings with a price cut
19%
US: 21%
Homes for sale vs pre-pandemic
+12%
US: −7%
October 2026 vs the October average for 2017 to 2019.

Market score by county

Check any county
Okaloosa County: 41 out of 100Glades County: 16 out of 100DeSoto County: 32 out of 100Dixie County: 4 out of 100Martin County: 53 out of 100Hardee County: 23 out of 100Bay County: 25 out of 100Flagler County: 60 out of 100Orange County: 53 out of 100Walton County: 31 out of 100Pasco County: 56 out of 100St. Lucie County: 48 out of 100Washington County: 47 out of 100Sumter County: 79 out of 100Palm Beach County: 46 out of 100Alachua County: 51 out of 100Lafayette County: 25 out of 100Okeechobee County: 36 out of 100Hernando County: 61 out of 100Charlotte County: 37 out of 100Lee County: 32 out of 100Lake County: 70 out of 100Suwannee County: 25 out of 100Levy County: 33 out of 100Nassau County: 62 out of 100Madison County: 33 out of 100Columbia County: 29 out of 100Calhoun County: 18 out of 100Citrus County: 54 out of 100Franklin County: 11 out of 100Gadsden County: 12 out of 100Gulf County: 18 out of 100Jefferson County: 40 out of 100Pinellas County: 34 out of 100Clay County: 78 out of 100Santa Rosa County: 83 out of 100Seminole County: 56 out of 100Volusia County: 38 out of 100Monroe County: 14 out of 100St. Johns County: 77 out of 100Osceola County: 37 out of 100Sarasota County: 62 out of 100Gilchrist County: 30 out of 100Hendry County: 18 out of 100Highlands County: 36 out of 100Indian River County: 50 out of 100Manatee County: 65 out of 100Union County: 30 out of 100Duval County: 70 out of 100Wakulla County: 73 out of 100Jackson County: 51 out of 100Leon County: 58 out of 100Escambia County: 60 out of 100Miami-Dade County: 21 out of 100Bradford County: 18 out of 100Taylor County: 23 out of 100Broward County: 26 out of 100Polk County: 57 out of 100Brevard County: 63 out of 100Hamilton County: 31 out of 100Collier County: 24 out of 100Baker County: 45 out of 100Liberty County: 19 out of 100Holmes County: 26 out of 100Putnam County: 29 out of 100Marion County: 49 out of 100Hillsborough County: 48 out of 100
Leans to buyersLeans to sellers

Gray counties had too few listings to score. Tap a county for its full answer.

Source: Realtor.com® Economic Research, October 2026 county data. County days on market are medians. State and US figures weight each county by its homes for sale. Price-cut share is the share of listings with a price reduction.

Judicial

How foreclosure works in Florida

Florida foreclosures go through court.

Main steps and notices
  • The lender files suit and serves the borrower.
  • If the lender wins, the sale is published once a week for two weeks, the second at least five days before the sale.
  • The sale usually takes place 20 to 35 days after the judgment.
  • After the certificate of sale is filed, the borrower has 10 days to object.
Catching up before the sale
State law does not require a right to reinstate.
After the sale
The borrower can redeem until the clerk files the certificate of sale, or the deadline set in the judgment. There is no redemption after that.
Before any of this starts
Under federal rules, a mortgage servicer generally can't make the first notice or filing for foreclosure until the borrower is more than 120 days behind.
Governing law
Florida Statutes § 45.031; § 95.11; § 702.06

Sources

General information, not legal advice.

Laws change and each case differs. Anyone facing foreclosure should talk with a local attorney or a HUD-approved housing counselor.

Florida questions

Is foreclosure in Florida judicial or non-judicial?

Florida foreclosures go through court.

Can a homeowner get the home back after a foreclosure sale in Florida?

The borrower can redeem until the clerk files the certificate of sale, or the deadline set in the judgment. There is no redemption after that.

Can a borrower in Florida catch up on the loan before the sale?

State law does not require a right to reinstate.

Is Florida a buyer's or seller's market right now?

A balanced market. Florida scores 43 out of 100 on our market scale, where low scores lean to buyers. Listings spent about 79 days on the market, and 19% had a price cut in October 2026. Source: Realtor.com® Economic Research.

How far behind does a borrower have to be before foreclosure starts?

Under federal rules, a mortgage servicer generally can't make the first notice or filing for foreclosure until the borrower is more than 120 days behind. Source: Consumer Financial Protection Bureau.